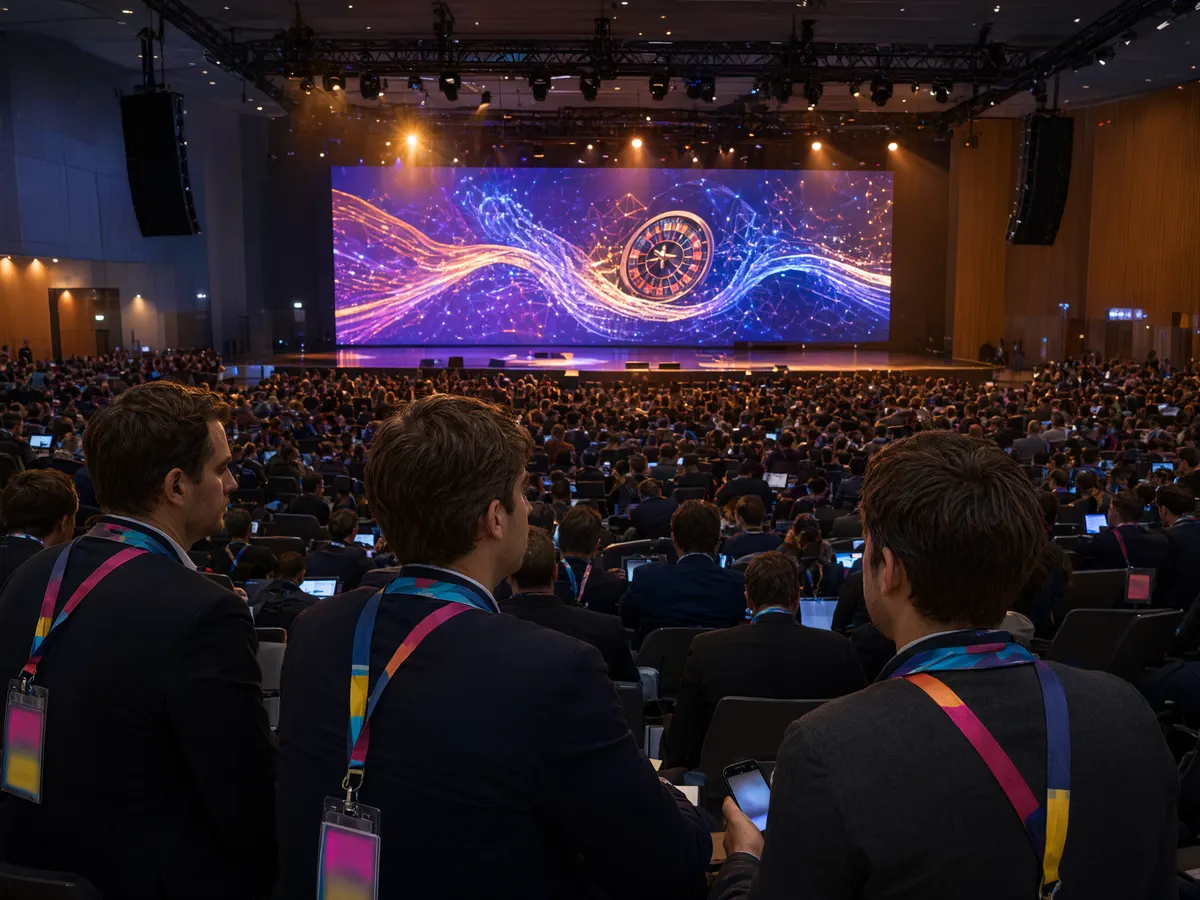
By mid-morning on opening day, the queue for coffee outside the main auditorium is longer than the queue for the keynote. That is not a criticism of the programme. It is the whole point of a show like this: the stage tells you what the industry wants to be seen caring about, and the corridors tell you what it is actually worried about. The two rarely match.
So here is the thesis behind these SBC Summit Lisbon highlights, and the rest of this piece argues it: the headline booking for Day 1 was a sports icon, but the substance sitting underneath the 2026 agenda is unglamorous plumbing. Payments, licensing costs, compliance workload, and content that keeps players engaged without leaning harder on the same slot mechanics. If you only read the headlines, you get the celebrity. If you read the agenda, you get the year ahead.
Why a Michael Jordan booking is itself the story
SBC’s own live coverage billed Michael Jordan as the name headlining Day 1 in Lisbon (SBC Americas live blog). I am not going to put words in his mouth that I did not hear, and neither should anyone else writing up a conference from a distance. The booking is the signal, not the soundbite.
Think about what a keynote slot of that size costs and what it buys. An industry conference books a global sports figure when it wants to be read as a mainstream media and entertainment business rather than a niche vertical. That framing has been building for years through shirt sponsorships, broadcast integrations and league partnerships, and it cuts both ways. Mainstream visibility brings mainstream scrutiny: advertising rules, sponsorship restrictions in several European markets, and politicians who now understand exactly how prominent betting brands have become in sport.
The practical read for operators and affiliates is simple. The sponsorship era is not over, but it is being repriced. Brand partnerships are increasingly judged on whether they survive a regulatory review, not just on reach.
Payments was the real main stage
Ask anyone who has run an operator P&L where the fastest wins are, and they will not say a new slot lobby. They will say payments. Every percentage point of failed deposits is revenue that never arrives, and every extra minute of withdrawal delay is a support ticket and a churn risk.
The direction of travel across regulated markets has been consistent: money is moving to instant, account-to-account rails. India has UPI. Brazil has Pix. Europe is building on open banking and instant SEPA transfers. These systems change player expectations in a way that is hard to walk back. Once someone can deposit in five seconds from their banking app, a three-day card withdrawal feels broken rather than normal.
That expectation collides with two things operators cannot skip. The first is KYC. Identity verification is a licence condition in regulated markets, and it is the single most common reason a first withdrawal takes longer than a first deposit. The second is affordability and source-of-funds checking, which in some jurisdictions now sits inside the payment journey rather than beside it.
The interesting conversation in Lisbon was not “faster payouts, good”. It was how to run tighter checks without adding friction that kills conversion, which usually means pulling verification earlier, automating document review, and being honest with players about why a withdrawal is pending. For readers who are players rather than operators: complete your KYC when you register, not when you want your money. It is the cheapest thing you can do to speed up a payout.
Regulation: everyone agrees on the principles, nobody agrees on the rules
The compliance sessions at a modern iGaming industry conference sound repetitive until you notice how little of it is harmonised. There is broad agreement on the goals — licensed supply, player protection, keeping minors out, curbing the black market. There is almost no agreement on the mechanics.
The examples are easy to name. Brazil moved from a grey market to a licensed regime, with federal licensing and tax obligations reshaping who could afford to operate there at scale. The Netherlands, Belgium, Germany and Italy have each taken different positions on advertising, sponsorship and deposit or stake controls. The UK has spent recent years layering on affordability checks, game design rules and levy arrangements. Multiply that by the US, where regulation is state by state and iGaming legalisation has moved far slower than sports betting.
The cost of that fragmentation is the part worth internalising. Compliance is now a fixed cost that scales badly for small operators and suppliers. Every new market means separate licensing, separate reporting, separate game certifications, sometimes separate technical hosting. That is one of the honest reasons consolidation keeps happening: the regulatory overhead rewards size.
Product: the search for something that is not another slot
Content discussion at events like this has shifted from graphics to mechanics and retention. A few threads keep recurring and they are worth separating from the marketing language around them.
- Crash and instant games. Titles in the Aviator mould have earned a permanent place in lobbies because rounds are short, the rules fit in one sentence, and many are provably fair, letting players verify a round’s outcome cryptographically. That transparency is a genuine product advantage, not just a feature list item.
- Live dealer localisation. Teen Patti, Andar Bahar and region-specific game shows exist because generic roulette tables do not convert everywhere equally.
- AI where it actually works. The useful applications being discussed are unglamorous: fraud detection, document verification, and behavioural models that flag risky play patterns for intervention. Personalised recommendation engines get more stage time, but the compliance-side use cases are the ones regulators will ask about.
- Volatility as a marketing tool. Studios increasingly ship one game with selectable volatility. Worth remembering that volatility changes how wins are distributed, not the return to player. A high-volatility mode is swingier, not more generous.
Three themes, and what each one actually changes
If you want the Lisbon agenda compressed into something you can act on, this is the shape of it.
| Theme | What to watch next | Practical implication |
|---|---|---|
| Payments and payouts | Adoption of instant account-to-account rails; earlier KYC in the sign-up flow | Withdrawal speed becomes a competitive feature, not a back-office metric |
| Regulation and cost of entry | Licence fees, tax rates, advertising and sponsorship restrictions per market | Fewer, larger operators per market; suppliers pick markets more selectively |
| Product and retention | Instant/crash formats, localised live tables, AI in risk and verification | Lobby mix shifts toward short-session games; RG tooling becomes a product surface |
How to read a summit without being sold to
A calm way to process any large sports betting summit or iGaming event takeaways round-up: ignore the superlatives and track the repetition. When four unrelated panels independently land on the same problem, that problem is real. When one company’s stand and three of its sponsored sessions push the same phrase, that is a campaign.
Apply that filter to Lisbon 2026 and the repeated problems were payment friction, compliance cost and retention in saturated markets. The repeated campaign words were AI and personalisation. Both matter, but only one set is keeping executives awake.
Common questions about SBC Summit Lisbon
What is SBC Summit?
SBC Summit is a large business-to-business conference and exhibition for the sports betting and iGaming industry, run by SBC. The Lisbon edition is its flagship European event, combining a conference programme with an exhibition floor and side events. Details of each edition are published on SBC’s event site.
Who attends, and is it open to players?
It is a trade event. Attendees are operators, game studios, payment providers, affiliates, regulators, law firms and sports rights holders. It is not a consumer event, and it is restricted to adults working in the sector.
Why do gambling industry trends get set at conferences?
They do not get set there so much as revealed there. Licensing decisions, tax changes and technology adoption happen over months; a summit is where the sector compares notes and discovers which problems are shared. That is why the agenda is a reasonable leading indicator of the next 12 months.
What should a player take from all this?
Two things. Faster, cleaner payments and stronger verification are becoming standard in licensed markets, so choose sites that hold a licence you can verify. And remember the maths has not changed: every game carries a house edge, so a 96% RTP slot means roughly 4% is retained by the operator over the long run. Set deposit and session limits before you play, use cool-off or self-exclusion tools if play stops being fun, and treat gambling as paid entertainment rather than income.